

PHOTO: Real Estate Institute of Queensland (REIQ). FILE
A controversial rule used in Queensland’s property transactions has changed after it caused home buyers to lose their life savings.
Last month, the Real Estate Institute of Queensland (REIQ) flagged that it would be releasing a new edition of the Houses and Land and Residential Community Title.
That change came into effect at the end of last week, on January 20.
Before the contract rules were amended, Queensland was the only Australian state that didn’t grant a two-week grace period if a property settlement deadline fell through.
It meant once the contract was over, the Queensland vendor was legally entitled to pocket the purchaser’s entire 10 per cent home deposit, meaning the buyer can lose everything.
But that’s all changed.
Last year, news.com.au reported on engaged couple Mark Trau and Maddie Goyder losing a $75,000 home deposit – that they had been saving up since teenagers — because a manual error meant their bank was 24 hours late at settling.
In an even more extreme case, Brisbane epidemiologist Dr Loretta McKinnon lost her dream home after the Commonwealth Bank delayed by 13 minutes on the date of settlement.
The update to the contractual requirements of a Queensland property deal has changed this “sudden death” rule however, there’s still a major catch.
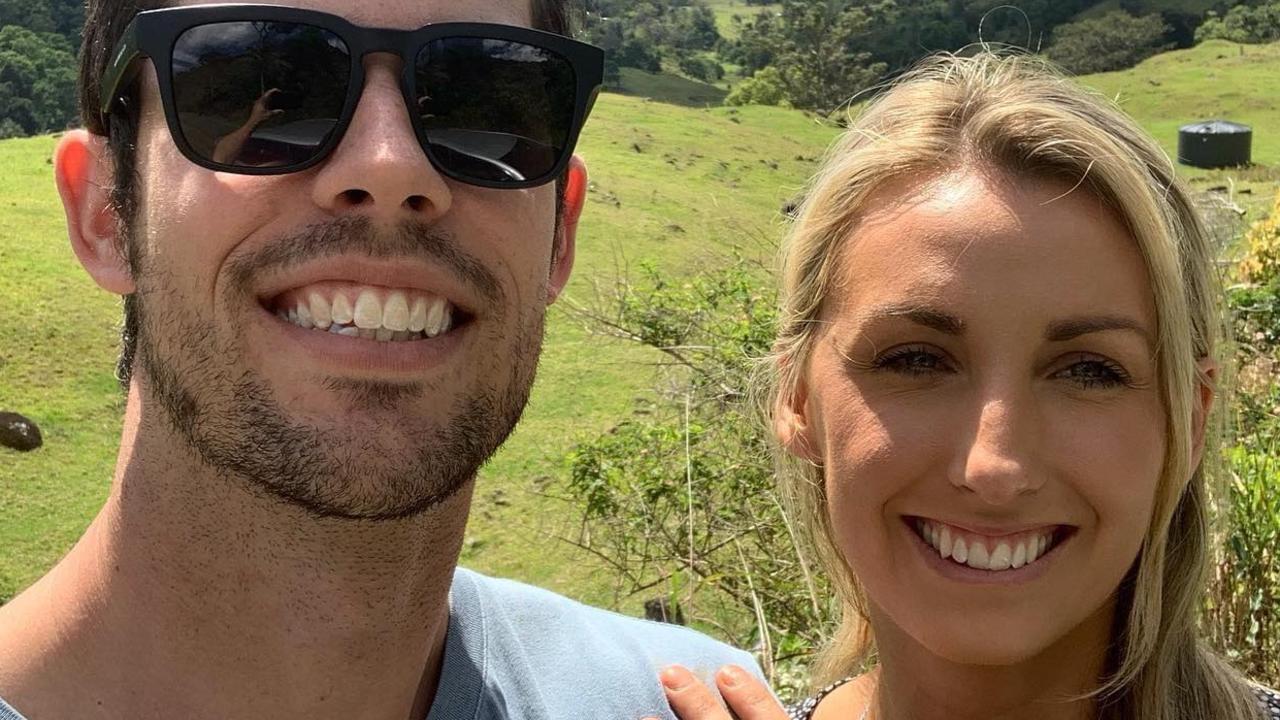
Mark Trau and Maddie Goyder were ‘stung’ by the largely unknown rule earlier this year.
REIQ chief executive Antonia Mercorella previously told news.com.au that the state‘s contractual requirements were changing after her institute heard about deals falling through at the 11th hour.
“Because of the volume of transactions that’s happening and because of Covid-19, banks are often causing delays. What we’ve been seeing is that banks are often not ready. Obviously we recognise that is outside the control of either party,” she said.
READ MORE VIA NEWS.COM.AU
https://www.instagram.com/p/CZAKs5hh-X1/?utm_source=ig_web_copy_link


